Quick Answer: You legally need travel insurance for Europe only if you are applying for a Schengen visa — the EU Visa Code requires medical cover of at least €30,000, valid across the whole Schengen area for your entire stay. Visa-exempt visitors, including UK, US, Canadian and Australian citizens, are not legally required to hold a policy. Even so, a single emergency hospital stay or a medical flight home can cost thousands of euros, so most travellers still buy cover.
It is one of the most-searched travel questions in Europe, and the answer is genuinely confusing: some travellers are turned away at the visa appointment without insurance, while others cross the same border with nothing at all and nobody asks. Both are correct — because the rule depends on who you are, not where you are going. A traveller from India, Pakistan, Nigeria or China faces a different requirement from a traveller from the UK, the US or Australia, even if they land on the same flight.
This guide explains who must have travel insurance for Europe in 2026, what the €30,000 Schengen rule actually requires, what the EHIC and GHIC health cards do and do not cover, what a policy typically costs, and the situations where travelling without cover is a real financial risk. Prices are indicative estimates based on published 2026 market ranges — your own premium depends on your age, destination, trip length and cover level. This is general information, not financial or legal advice.
Do I legally need travel insurance to visit Europe?
For most visitors, no. There is no general European law that requires tourists to hold travel insurance. If you are a citizen of a visa-exempt country — the UK, the United States, Canada, Australia, New Zealand, Japan and others — you can enter the Schengen area without showing any insurance policy, and border officers do not routinely ask for one. Your trip is legal without cover, and no airline will refuse to board you for lacking it.
The exception is the Schengen visa itself. If your nationality requires a short-stay Schengen visa, the EU’s Visa Code (Regulation (EC) No 810/2009, Article 15) makes travel medical insurance a condition of the application: your policy must cover at least €30,000 of medical costs, be valid in every Schengen state, cover your whole intended stay, and include medical repatriation, urgent medical attention, emergency hospital treatment and repatriation of remains. A policy that misses any of those elements can lead to a refused visa — and consulates do check. Our Schengen visa travel insurance guide walks through the exact wording consulates look for.
Two other cases are worth knowing. Some long-stay visa and residence-permit applications — for study, work or family reunion in countries such as Germany, France or Spain — also require proof of health cover, though the requirement there is usually for full health insurance rather than a short travel policy. And a small number of countries outside the Schengen area have their own entry insurance rules, so always check the destination’s own requirements rather than assuming the Schengen rule is the only one.
What does the €30,000 Schengen insurance rule actually require?
The €30,000 figure is a legal floor, not a recommendation. It was set to cover the realistic cost of emergency hospital treatment plus a medical flight home from anywhere in the Schengen area, and it applies to every short-stay (type C) visa application across all 29 Schengen states. The rule has four tests, and a policy must pass all of them.
| Requirement | What it means in practice | Common reason for refusal |
|---|---|---|
| Minimum €30,000 medical cover | At least €30,000 of emergency medical expenses | Policy in another currency that dips below €30,000 on the appointment day |
| Valid in all Schengen states | Cover must say “Schengen area” or list all member states | Policy valid only in the first country, e.g. “France only” |
| Valid for the whole stay | From the day you enter to the day you leave | Policy dates shorter than the trip dates |
| Repatriation included | Medical repatriation and repatriation of remains | Missing repatriation wording in the policy document |
Many travellers buy a policy with a €50,000 or €100,000 limit rather than exactly €30,000, precisely because a policy in pounds or dollars can slip below the euro threshold if the exchange rate moves before the appointment. A zero-excess (no deductible) policy is also safer for visa purposes, because a high excess reduces the effective cover the consulate counts. If you buy a Schengen-compliant policy from a European insurer, the certificate usually states the €30,000 figure and the Schengen validity explicitly — that wording is what the visa officer looks for, so keep the certificate with your application file.
Does the EHIC or GHIC replace travel insurance?
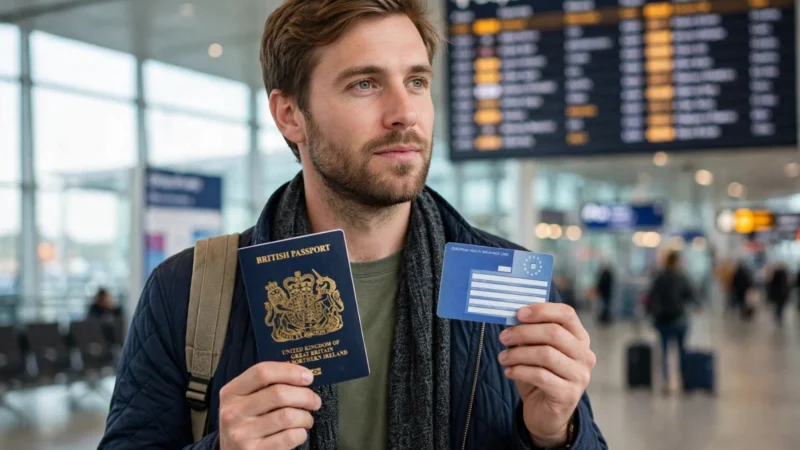
No — and this is the most common misunderstanding in European travel. The European Health Insurance Card (EHIC) and the UK’s Global Health Insurance Card (GHIC) give you access to medically necessary state-provided healthcare in the EU on the same terms as local residents. They are free, and for EU citizens the EHIC comes from your own health insurer, while UK residents get the GHIC free from the NHS. The cards are genuinely useful — but they are not travel insurance, and both the European Commission and the NHS say so explicitly.
The gap is what the cards do not pay for. They do not cover private hospital treatment, they do not pay for medical repatriation — being flown home after a serious accident — and they do not cover mountain rescue, trip cancellation, lost luggage or missed flights. They also only cover state healthcare on local terms, which in some countries means you still pay part of the bill yourself, exactly as a local resident would. A broken leg on a ski slope in France or Austria, for example, can involve a helicopter rescue costing several thousand euros, and neither card pays for that.
The practical advice from the NHS itself is to carry both: the GHIC for state healthcare, and a private travel policy for everything else. The same logic applies to EHIC holders. And neither card satisfies a Schengen visa application — a visa applicant still needs a proper travel medical policy with the €30,000 minimum, because the visa rule explicitly requires repatriation cover that the cards do not provide.
When should I buy travel insurance even if it is not required?
Legally optional is not the same as financially safe. The question to ask is not “must I?” but “what happens if something goes wrong?” A single night in a European hospital can cost €1,000–€3,000, an emergency operation far more, and a medical flight home — an air ambulance — can cost €15,000–€50,000 depending on distance and medical needs. A basic travel policy that costs less than a dinner out can absorb all of that.
There are five situations where going without cover is a genuinely bad idea. First, winter sports: skiing and snowboarding injuries are common, mountain rescue is expensive, and standard policies often exclude winter sports unless you add the cover. Second, travelling with a pre-existing medical condition — a hospital that treats you without a policy will bill you directly, and the bill follows you home. Third, travelling with children or elderly parents, where a single illness can strand the whole group. Fourth, trips involving expensive prepaid bookings, where cancellation cover protects money you cannot recover otherwise. And fifth, any trip where you plan adventure activities — hiking in the Alps, scuba diving in Greece, cycling in the Pyrenees — because rescue and private treatment costs rise sharply with remoteness. Our Europe travel insurance guide explains which cover levels suit each type of trip.
There are also travellers for whom the risk is genuinely low: a healthy young adult on a short city break in a country with a strong public health system, carrying an EHIC, staying in a hotel with a flexible booking, and able to absorb a few hundred euros of unexpected cost. Even then, the policy is cheap enough that most travel advisers still recommend it — the premium for a week in Europe is usually a small fraction of the flight cost.
How much does travel insurance for Europe cost in 2026?
For a healthy adult, a single-trip policy for a week in Europe typically costs roughly €20–€60 for basic medical and cancellation cover, rising to about €60–€120 for comprehensive cover with higher medical limits and winter sports or adventure add-ons. Annual multi-trip cover for someone who travels to Europe several times a year usually costs roughly €100–€250, and is often cheaper than three separate single-trip policies. Older travellers pay more: a traveller over 65 can expect roughly double the standard premium, and cover for pre-existing conditions adds a further amount depending on the condition. These are indicative market ranges for 2026 — the exact price depends on your age, destination countries, trip length and the medical limit you choose.
| Trip type | Typical cost (2026, indicative) | What it usually includes |
|---|---|---|
| Single trip, 1 week, adult under 65 | €20–€60 | Medical cover, cancellation, baggage |
| Single trip, 1 week, comprehensive | €60–€120 | Higher medical limits, winter sports or adventure options |
| Annual multi-trip (Europe) | €100–€250 | Unlimited trips, usually up to 30–45 days each |
| Schengen visa policy (single trip) | €15–€50 | Meets the €30,000 minimum, repatriation included |
| Traveller over 65, 1 week | €50–€150 | Age-rated; pre-existing conditions extra |
What actually drives the price is the medical limit you choose, your age, and the activities you declare. A €30,000 medical limit is the visa minimum, but most advisers suggest at least €100,000 — and the price difference is usually small. Always declare pre-existing conditions: an undeclared condition is the most common reason a medical claim is refused, and it can leave you with the full hospital bill. Buying the policy the same day you book the trip also matters, because cancellation cover only protects bookings made after the policy starts.
What about ETIAS and the Entry/Exit System in 2026?
Two new EU border systems cause confusion about insurance, so the facts are worth stating plainly. The Entry/Exit System (EES), which records the entry and exit of non-EU visitors, became fully operational at external Schengen borders on 10 April 2026. ETIAS, the travel authorisation that visa-exempt visitors will eventually need, is not in operation yet — no applications are being collected, and the European Commission will announce the start date and the €20 fee several months before launch. The only reliable source for ETIAS timing is the EU’s own travel portal at travel-europe.europa.eu.
Neither system creates a travel-insurance requirement. EES is a border-recording system and ETIAS is a pre-travel authorisation — neither asks for an insurance certificate. The insurance rule for travellers who need a Schengen visa is separate, and it has not changed: the €30,000 minimum under the Visa Code still applies. If a website tells you ETIAS requires you to buy insurance, it is selling you a policy, not stating the law.
How do I choose the right policy for a Europe trip?
Start with your own situation, not with the cheapest price. First, check whether you need a visa: if you do, the policy must meet the €30,000 rule and the certificate must say so. Second, check what your EHIC or GHIC already gives you — it covers state healthcare, so your private policy is mainly buying repatriation, private care, cancellation and baggage cover. Third, match the medical limit to the risk: €100,000 or more is the sensible floor for most trips, and winter sports or a cruise pushes it higher.
Then read the exclusions before you buy. Check whether winter sports, scuba diving, hiking above a certain altitude or riding a motorbike are covered or excluded. Check the alcohol exclusion, which is standard in almost every policy and voids claims where drinking contributed to the accident. Check the excess: a €100 excess on a €300 claim means you pay the first €100 yourself, and on a visa application a high excess can be a problem. Finally, save the emergency assistance number in your phone before you travel — in a real emergency you call the insurer’s assistance line first, not your travel agent, because the insurer arranges and pays for the hospital and the flight home. Travellers from the UK should also read our guide for UK citizens travelling to Europe after Brexit, which covers GHIC rules in detail.
Key Takeaways
- Travel insurance for Europe is legally required only for Schengen visa applicants — medical cover of at least €30,000, valid across the whole Schengen area for the entire stay.
- Visa-exempt visitors (UK, US, Canada, Australia and others) are not legally required to hold a policy, but a hospital stay or medical flight home can cost thousands of euros without one.
- The EHIC and GHIC cover state healthcare only — they do not pay for private treatment, repatriation, mountain rescue, cancellation or lost luggage, and they do not satisfy a visa application.
- A week’s cover for Europe typically costs roughly €20–€60 for a healthy adult, and annual multi-trip cover roughly €100–€250 — a small fraction of the trip cost.
- ETIAS is not yet in operation and neither ETIAS nor the Entry/Exit System creates an insurance requirement.
- Declare pre-existing conditions, buy the policy when you book the trip, and save the insurer’s emergency number before you travel.
Frequently Asked Questions
Do I need travel insurance for Europe?
Only if you are applying for a Schengen visa — the EU Visa Code requires medical cover of at least €30,000. Visa-exempt visitors are not legally required to hold a policy, but most travellers still buy one because a hospital stay or a medical flight home can cost thousands of euros.
Is travel insurance mandatory for a Schengen visa?
Yes. Under Article 15 of the EU Visa Code, short-stay visa applicants must show travel medical insurance covering at least €30,000, valid in all Schengen states for the whole stay, including medical repatriation, urgent medical attention, emergency hospital treatment and repatriation of remains.
Can I travel to Europe with just an EHIC or GHIC?
You can travel, but the card is not travel insurance. It gives you state healthcare on local terms, but it does not cover private treatment, repatriation, mountain rescue, cancellation or lost luggage. The NHS advises UK travellers to carry both the GHIC and a private policy.
How much does travel insurance for Europe cost?
A single-trip policy for a week in Europe typically costs roughly €20–€60 for a healthy adult under 65, and comprehensive cover roughly €60–€120. Annual multi-trip cover usually costs about €100–€250. Older travellers and pre-existing conditions increase the premium.
Does ETIAS require travel insurance?
No. ETIAS is a pre-travel authorisation for visa-exempt visitors and it is not yet in operation. It does not ask for an insurance certificate. The only insurance requirement in Europe is the Schengen visa rule under the Visa Code.
What does travel insurance for Europe usually cover?
A standard policy covers emergency medical treatment, medical repatriation, trip cancellation, missed departure, lost or delayed baggage and personal liability. Winter sports, adventure activities and pre-existing conditions are often excluded unless declared and added to the policy.
Do I need travel insurance for a trip to Ireland or the UK?
Ireland and the UK are outside the Schengen area, so the €30,000 Schengen visa rule does not apply to them. The same practical logic applies though: your EHIC or GHIC covers state healthcare, but repatriation, private care and cancellation still need a travel policy.
When should I buy travel insurance for Europe?
Buy it the day you book your trip. Cancellation cover only protects bookings made after the policy starts, so buying late leaves your deposit and flights unprotected. For a visa application, buy it before your appointment so the certificate is in your file.
Disclaimer: This article is general information about travel insurance for Europe, not financial or legal advice. Prices are indicative estimates for 2026 and vary by insurer, age, destination and cover level. Visa and border rules change, so always check the current requirements with the relevant consulate and the EU’s official travel portal before travelling. Europe Insurance Guide is an independent guide and is not affiliated with the European Commission, the NHS or any insurer named here.

About the author
Written by Mehboob Ahmed
Mehboob Ahmed is the founder and editor of Europe Insurance Guide. He researches, writes and reviews the site's guides, checking facts against official European sources and updating them when rules or prices change.
Meet the Founder → More about Europe Insurance Guide →