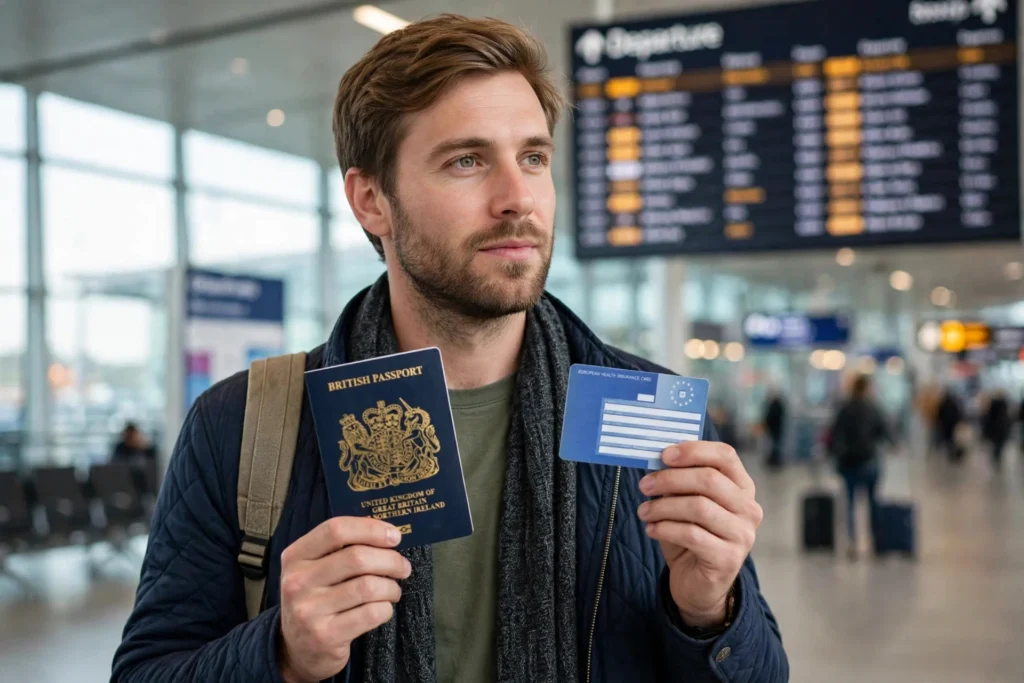
Quick Answer: Yes. UK citizens still need travel insurance for Europe after Brexit. The free UK Global Health Insurance Card (GHIC) covers state-provided, medically necessary treatment in the EU and Switzerland, but it does not cover private hospitals, medical repatriation, mountain rescue, cancelled trips or lost luggage — and those are the costs that can run into tens of thousands of pounds.
Before Brexit, travelling to Europe felt simple for British holidaymakers: pack the EHIC, and the health system would look after you. The card still exists in a new form, but the deal behind it changed, and the most dangerous misunderstanding since 2021 is the idea that the GHIC replaced travel insurance. It did not. Every year, British travellers discover the gap the expensive way — in a private clinic in Spain, on a stretcher in a French ski resort, or facing a £15,000 air ambulance bill.
This guide explains exactly what changed after Brexit, what the GHIC covers and what it misses, how much travel insurance costs in 2026, and what to buy for a city break, a ski trip or a long stay. Prices are indicative estimates based on published 2026 figures. This is general information, not financial or medical advice.
What changed for UK travellers after Brexit?
When the UK left the EU, British citizens lost the automatic right to live, work and use public services in EU countries. For travel, three things changed that matter for insurance. First, the EHIC was replaced by the UK Global Health Insurance Card (GHIC) — same idea, slightly narrower coverage. Second, UK visitors to the Schengen area are now limited to 90 days in any 180-day period, which affects long stays and second-home owners. Third, UK driving licences, pet travel and mobile roaming all changed, but for health the GHIC is the card that matters.
The UK government still advises all travellers to take out comprehensive travel insurance, and the advice is blunt: the GHIC is not a substitute for travel insurance. That is the official position on the NHS and GOV.UK travel pages, and it is worth taking seriously, because the gap between what the GHIC covers and what a real medical emergency costs is where the financial damage happens. Our complete travel insurance guide for Europe explains the cover levels in detail.
What is the GHIC and what does it cover?
The UK Global Health Insurance Card is free, and it entitles UK residents to state-provided, medically necessary healthcare during temporary stays in EU countries and Switzerland — treatment that cannot wait until you get home. Apply for it free on the NHS website, and beware of unofficial sites that charge a fee for the same application; the card itself costs nothing and usually arrives within ten working days.
In practice, the GHIC works like the old EHIC in most EU countries: show it at a state hospital or clinic and you get treatment on the same terms as a local resident. That can mean free treatment in countries like Spain, or treatment with a patient co-payment in countries like France, where locals pay part of the bill themselves. It covers emergency treatment, treatment for pre-existing conditions that need attention while you are away, routine maternity care and, in most countries, oxygen and dialysis for people who need them. Existing UK-issued EHICs remain valid until their printed expiry date, so check your wallet before you apply for a GHIC — you may already be covered for this trip.
One important limit: the GHIC is only for temporary stays. It does not cover you if you move to an EU country to live, and it does not cover treatment you travel abroad specifically to receive. If you are moving to Europe, you need proper residence health cover — our Europe health insurance guide explains the residence rules country by country.
Which countries does the GHIC cover?
The GHIC is valid in all EU member states plus Switzerland. That covers the places British travellers visit most: France, Spain, Italy, Germany, Portugal, Greece and the rest. Norway, Iceland and Liechtenstein are not covered by the GHIC, so a trip to the Norwegian fjords or an Iceland holiday needs travel insurance with no state back-up at all — check the GOV.UK foreign travel advice pages for the current position before you travel. The card is also not valid in the Channel Islands or the Isle of Man, which are not part of the UK for healthcare purposes.
What the GHIC does not cover
This is the list that matters, because every item on it is a bill that travel insurance normally pays. The GHIC does not cover private hospitals or private treatment — and in many popular resorts, the nearest clinic is private. It does not cover medical repatriation: if you need an air ambulance home, that is roughly £15,000–£25,000 from Spain or the Canary Islands, paid by you. It does not cover mountain rescue, which in the Alps is charged by the hour and can run to thousands of euros. It does not cover cancelled or cut-short trips, missed departures, lost luggage or stolen belongings. And it does not cover the cost of a relative travelling to be with you, or of extra hotel nights while you recover.
A real example makes the point. A British skier breaks a leg in the French Alps and is taken by helicopter to a private clinic. The GHIC may cover part of the state-hospital treatment, but the helicopter rescue, the private clinic stay, the repatriation flight home and the cancelled week of the holiday are all outside it. Travel insurance with winter sports cover pays all of them. Without it, the bill can exceed £20,000 for a single accident. Our emergency medical coverage guide breaks down what emergency treatment actually costs across European countries.
Do UK citizens need a visa or travel insurance for a Schengen trip?
For short tourist trips, no visa is needed: UK passport holders can visit the Schengen area visa-free for up to 90 days in any 180-day period. But travel insurance is a different question from visas. Schengen visa applicants from countries that need a visa must hold travel insurance with at least €30,000 of medical cover, valid in all Schengen states — and while UK citizens do not need that visa, the €30,000 figure is a useful benchmark for the minimum medical cover worth buying. Our Schengen visa travel insurance guide explains the requirement in full.
From 2026, the EU’s ETIAS travel authorisation is being introduced for visa-free visitors including UK citizens. ETIAS is not insurance and does not change the insurance position, but it is one more reason to get the paperwork right before departure. And if you plan to stay longer than 90 days — for a second home or a long winter in Spain — you need a visa and a long-stay health insurance policy, not a holiday policy.
How much does travel insurance for Europe cost in 2026?
For a healthy adult, Europe travel insurance is cheap compared with the risk it covers. Indicative 2026 prices: a single-trip policy for a week in Europe typically costs £15–£40, an annual multi-trip European policy £60–£150, and a family annual policy £120–£250. Age, pre-existing medical conditions, winter sports cover and trip length push the price up; a 70-year-old with a heart condition will pay several times more than a healthy 30-year-old, and a policy that includes the USA costs far more than a Europe-only one.
| Policy type | Typical cost in 2026 | Best for |
|---|---|---|
| Single trip, 1 week, Europe | £15–£40 | One-off holidays |
| Annual multi-trip, Europe | £60–£150 | Two or more trips a year |
| Family annual, Europe | £120–£250 | Families travelling together |
| Single trip with winter sports | £40–£90 | Ski and snowboard holidays |
| Long-stay / backpacker, 3–6 months | £150–£400 | Extended stays, sabbaticals |
| Over-65 or pre-existing conditions | £100–£400+ | Older travellers, medical cover |
The cheapest policy is rarely the best one. The number to compare is the medical expenses limit — look for at least £5 million, ideally £10 million — and check the excess, the cancellation limit, and whether your pre-existing conditions are actually declared and covered. A £15 policy with a £250 excess and a £1 million medical limit can leave you worse off than a £35 policy with a £50 excess and £10 million of cover. Always declare medical conditions: an undeclared condition can void the whole policy, and insurers do check medical records when a large claim is made.
What should a UK traveller’s Europe policy include?
At minimum, look for emergency medical expenses of £5–10 million, repatriation to the UK, cancellation and curtailment cover of at least £3,000, baggage cover of £1,500 or more, and personal liability cover. If you are skiing, add winter sports cover — standard policies exclude off-piste skiing and often exclude skiing entirely without the add-on. If you are cruising, check that the policy covers missed port departures and medical care on board. If you have a medical condition, declare it and get written confirmation that it is covered.
Check the small print on three things people miss. First, alcohol: most policies exclude claims arising from excessive alcohol consumption, and hospitals do record it. Second, the policy’s definition of a pre-existing condition, which is usually broader than people expect. Third, whether the policy covers you for the full trip including the day you travel home — a surprising number of claims happen on the last day.
Single trip or annual multi-trip: which is better?
The maths is simple: if you take two or more European trips a year, an annual multi-trip policy is usually cheaper than buying single-trip cover each time. A single week in Spain might cost £20–£30 as a one-off, while an annual European policy at £70–£100 covers unlimited trips of up to 31 days each. Annual cover also removes the risk of forgetting to buy insurance for a short trip, which is how many claims are lost. The exception is if you take one long trip a year: most annual policies cap each trip at 31 days, so a two-month stay needs a long-stay or single-trip policy instead. Our annual multi-trip travel insurance guide compares the options in detail.
Common mistakes UK travellers make in Europe
The first is travelling with only a GHIC and no insurance — the single most expensive mistake on this list. The second is buying the cheapest policy without checking the medical limit or the excess. The third is not declaring a medical condition, which can void a claim entirely. The fourth is assuming the GHIC covers Norway, Iceland and Liechtenstein — it does not. The fifth is forgetting that a UK EHIC or GHIC is for temporary stays only and offers nothing if you move to Europe. And the sixth is buying insurance after departure: almost no policy covers a trip that has already started, so buy before you leave the UK.
Key Takeaways
- Yes — UK citizens need travel insurance for Europe after Brexit. The GHIC is free state healthcare cover, not a replacement for insurance.
- The GHIC covers state-provided, medically necessary treatment in the EU and Switzerland, but not private care, repatriation, rescue, cancellation or baggage.
- Existing UK EHICs stay valid until they expire; apply for a GHIC free on the NHS website and ignore sites that charge for it.
- Budget £15–£40 for a single-trip week, £60–£150 for annual European cover; look for at least £5 million of medical cover and a low excess.
- Declare all medical conditions, add winter sports cover for ski trips, and buy before you leave — cover bought after departure rarely applies.
Frequently Asked Questions
Can UK citizens travel to Europe without travel insurance?
Legally, yes for short tourist trips — there is no insurance requirement for visa-free UK visitors. But travelling without it means paying private medical bills, repatriation and cancellation costs yourself, and the UK government strongly advises against it.
Is the GHIC the same as travel insurance?
No. The GHIC only covers state-provided, medically necessary treatment in the EU and Switzerland. It does not cover private treatment, medical repatriation, mountain rescue, trip cancellation, lost luggage or any of the other costs travel insurance pays.
Is my old EHIC still valid after Brexit?
UK-issued EHICs remain valid until the expiry date printed on the card. When it expires, apply for a free UK GHIC on the NHS website. Never pay a third-party site for a card — the GHIC is free.
Does the GHIC cover Spain and France?
Yes. The GHIC is valid in all EU member states, including Spain and France, plus Switzerland. In France you may still pay a patient co-payment, as French residents do; in Spain state treatment is usually free at the point of use.
How much is travel insurance to Europe from the UK?
Indicative 2026 prices: £15–£40 for a single week, £60–£150 for an annual multi-trip European policy, more for older travellers, pre-existing conditions or winter sports cover. Prices vary by age, health and trip length.
Do I need travel insurance for a cruise in Europe?
Yes, and check the policy specifically covers cruises: medical care on board, missed port departures and repatriation from the ship are often excluded from standard policies or need a cruise add-on.
What if I have a pre-existing medical condition?
Declare it when you buy the policy and get written confirmation of cover. Specialist medical travel insurers cover many conditions that standard insurers decline, but an undeclared condition can void a claim.
Brexit changed the card in your wallet, not the risk of travelling. The GHIC is a useful safety net for state treatment, but it is not insurance, and the gap between the two is measured in thousands of pounds when something goes wrong. Buy a proper policy before you leave, declare your health honestly, and check the medical limit and the excess — then enjoy the trip knowing the expensive surprises are covered. For the full picture of cover levels and costs, read our complete travel insurance guide for Europe.
Disclaimer: This article is general information about travel insurance and the GHIC, not financial or medical advice. Rules on the GHIC, ETIAS and entry requirements change; check the NHS and GOV.UK travel advice pages and confirm your policy wording with your insurer before you travel.

About the author
Written by Mehboob Ahmed
Mehboob Ahmed is the founder and editor of Europe Insurance Guide. He researches, writes and reviews the site's guides, checking facts against official European sources and updating them when rules or prices change.
Meet the Founder → More about Europe Insurance Guide →
1 comment